
“Luck is a matter of preparation meeting opportunity.”
Introduction
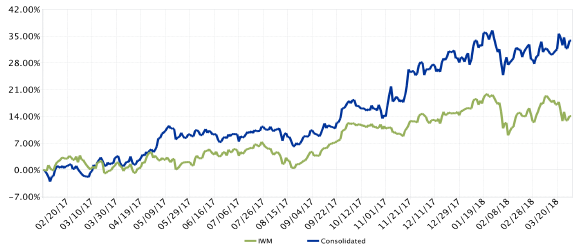
Welcome to Kehlet Capital Management’s inaugural quarterly newsletter. The goal of this and future letters will be to help you assess your investment with KCM. Unfortunately, evaluating performance is a difficult task. Like poker, investing requires skill but luck plays a significant role as well. From the outside looking in, it can often be challenging to decipher between the two. And since opportunities, in poker and investing, come around infrequently and at irregular intervals we often need to play many hands before we have the chance to earn outsized returns. It is for this reason that I recommend analyzing results over an extended period of time, ideally five years but certainly no less than three. This ensures a sufficient number of investment opportunities have presented themselves and that results reflect more skill than luck. As a result, my goal for KCM is to outperform the benchmark, net of fees, over any five-year period. If I fail to do so, I have not earned my pay and we should all look for alternative places to invest our money.
Performance
| Year | KCM Composite, Net | IWM | Excess Return |
|---|---|---|---|
| 2017* | 27.20% | 14.26% | +12.94% |
| YTD | 4.49% | -0.18% | +4.67% |
| Annualized | 27.82% | 12.02% | +15.80% |
*Inception date: 02/01/2017
The first quarter of 2018 was off to a good start with Kehlet Capital Management’s concentrated micro-cap composite up 4.49%, outperforming the benchmark which was down 0.18%. As luck would have it, preparation met opportunity during the quarter when I looked at a company called DXP Enterprises (DXPE). DXP is an industrial distributor of maintenance, repair, and operations (MRO) products used in oil & gas production as well as general manufacturing. It operates more than 175 locations in thirty-four U.S. states and nine provinces in Canada, while serving more than 50,000 customers. It is a business I have followed for years but had, until recently, never pulled the trigger on. But an opportunity to buy the stock at an attractive price presented itself during the first quarter that I could not pass up. Despite being a great business run by highly competent people, DXP has struggled over the last few years due to plummeting oil prices and severe spending cutbacks by its customers. Consequently, DXP’s stock price plunged nearly 90% from its peak of almost $113 per share to less than $13 in May of 2016. The decline was warranted but, over the next couple of years, oil prices and North American rig counts steadily began to recover while the company’s stock price lagged behind. After some additional research I concluded that there was a considerable chance the company would report earnings above expectations over the next few quarters and possibly years. The thesis started off well as the company reported organic revenue growth of 20%, operating income per share growth of over 50%, and the closing of its first major acquisition in over two years. The stock quickly jumped, increasing 29.59% during the quarter, and was consequently the largest driver of performance. Despite the cyclical nature of the oil and gas industry, DXP’s business model has proven extraordinarily resilient. Based on a continued recovery in the oil & gas and industrial markets, I expect to see sustained improvement from the company over the next few quarters as well.
We were not as fortunate with Astronics Corporation (ATRO) in Q1 and it was the biggest drag on performance, declining 10.32%. Astronics is a supplier of engineered components to the aerospace, defense, and semiconductor industries. Their main product line is called EmPower and provides electrical power to charge personal electronics and embedded in-flight entertainment systems on commercial aircraft. Simply put, if you have ever traveled on an international flight and watched a movie on a seatback TV while charging your phone through a plug in the armrest, chances are you have used Astronics’ products. And they have an incredible 90% share of this market. Similar to DXP, Astronics is a wonderful business that has struggled over the last few years due to a dramatic slowdown in production of widebody aircraft. But opportunity presented itself in the fourth quarter last year when the widebody market started to show signs of life and Astronics reported significant improvement in new orders and backlog (important leading indicators of the business). However, these developments had not yet revealed themselves in the company’s financial results, due to the long lead times required to convert orders into revenue. This likely caused misunderstanding among many investors who had only superficial knowledge of the business. But given the substantial improvement in the company’s leading indicators, I determined that significant increases in revenue and profitability would likely follow. I initiated a position within the portfolio in December 2017. Less than three months later Astronics reported weak quarterly results but accelerating strength in new orders and backlog. The divergence between current results and future expectations had grown wider, and with it the probability of misunderstanding among investors. As a result, my conviction in the idea increased during the first quarter despite the negative stock performance. Based on the significant momentum in the business, I am optimistic that the thesis will play out over the next couple of years.
Conclusion
First quarter results reflected a combination of preparation and opportunity. Some ideas worked out while others did not but overall, results were satisfactory. Although I cannot predict the timing in which opportunities present themselves, rest assured that I will work hard to stay prepared for when they do. If you have any questions, please do not hesitate to contact me. Thank you for supporting Kehlet Capital Management and entrusting me to invest on your behalf.
Disclosures to Performance Results
Actual composite performance results represent the performance of fully discretionary accounts managed by Kehlet Capital Management (KCM) during the corresponding time period. The composite performance results reflect time-weighted rates of return, the reinvestment of dividends and other account earnings. The reinvestment of dividends and other earnings may have a material impact on overall returns.
Past performance is not indicative of future results and the performance of a specific individual client account may vary substantially from the composite performance results. Therefore, no current or prospective client should assume that future performance will be profitable, or equal either the KCM composite performance results reflected above, or the performance results for any of the comparative index benchmarks provided.
For reasons including variances in portfolio account holdings, variances in the investment management fee incurred, market fluctuations, the date on which a client engages KCM’s investment management services, and any account contributions or withdrawals, the performance of a specific client’s account could vary substantially from the indicated KCM composite performance results. A portion of each account can be actively managed in an attempt to respond to changing conditions.
All performance results have been compiled solely by KCM, are unaudited, and have not been independently verified. Therefore, the performance data could be wrong. Information pertaining to KCM’s advisory operations, services, and fees is set forth in KCM’s current Form ADV Part 2A disclosure brochure, a copy of which is available from KCM upon request.
iShares IWM is an exchange-traded fund (ETF) measuring the performance of approximately 2,000 small-cap companies. It serves as a benchmark for small-cap stocks in the United States.
KCM managed accounts may own assets and follow investment strategies which cause them to differ materially from the composition and performance of the ETF shown as a benchmark. The ETF was chosen for its accessibility, transparency, independence, and relevance to KCM’s investment strategy, but there may be other indices that are more appropriate or applicable to the Concentrated Micro-cap Strategy. The historical index performance results are provided exclusively for comparison purposes only, so as to provide general comparative information to assist an individual client or prospective client in determining whether a specific Portfolio meets, or continues to meet, his/her investment objective(s). It should not be assumed that account holdings will correspond directly to any of the comparative indexes.
Different types of investments and/or investment strategies involve varying levels of risk, and there can be no assurance that any specific investment or investment strategy (including the investments purchased and/or investment strategies devised by KCM) will be either suitable or profitable for a client’s or prospective client’s portfolio and may result in a loss of principal. Accordingly, no client or prospective client should assume that the above portfolios (or any component thereof) serve as the receipt of, or a substitute for, personalized advice from KCM, or from any other investment professional.