
“The courage to start. The discipline to focus. The confidence to figure it out. The patience to know progress is not always visible. The persistence to keep going, even on the bad days. That’s the formula.”
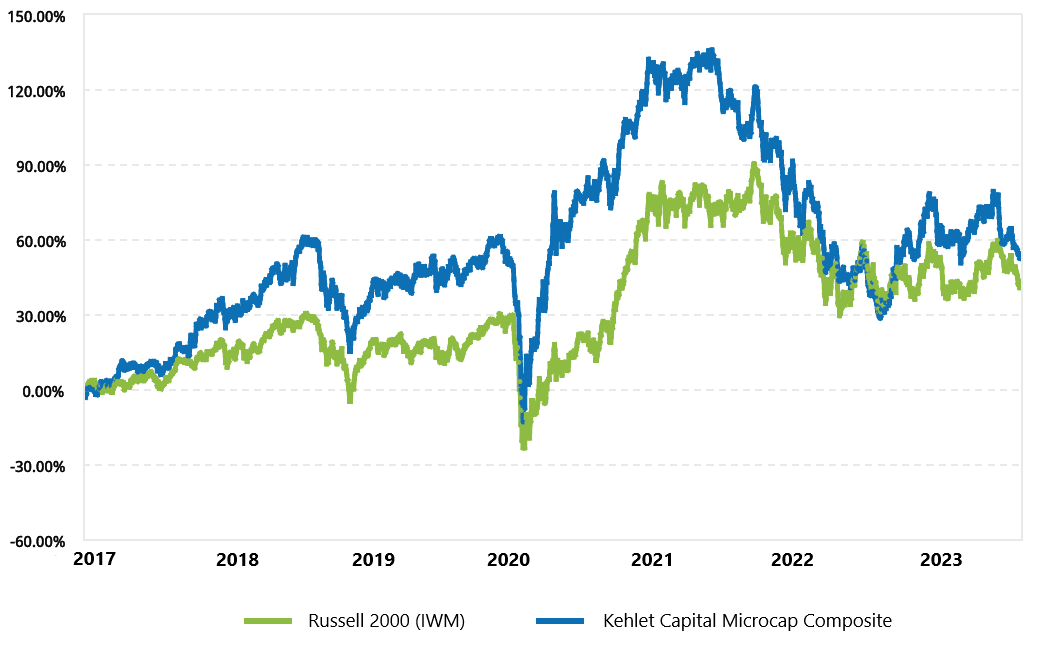
| Year | KCM Composite, Net | IWM | Excess Return |
|---|---|---|---|
| 2017* | 27.20% | 14.26% | +12.94% |
| 2018 | -3.43% | -11.11% | +7.68% |
| 2019 | 27.79% | 25.39% | +2.40% |
| 2020 | 27.52% | 20.03% | +7.49% |
| 2021 | -1.45% | 14.54% | -15.99% |
| 2022 | -22.63% | -20.48% | -2.15% |
| YTD 2023 | -0.69% | 2.50% | -3.19% |
| Annualized | 6.44% | 5.48% | +0.96% |
*Inception date: 02/01/2017
Introduction
I know this will come as a huge disappointment, but this quarter’s newsletter will be much shorter than usual. The reason is that I am currently in the middle of a project to automate several KCM processes and want to keep the momentum going. I have been working on this project for a couple of months now and there is still a lot of work to be done. Though I will provide more details in a future newsletter, I will say that I am excited about the project’s potential benefits. Most importantly, I expect it to significantly improve my idea generation process by allowing me to monitor custom metrics for 1,100+ companies in near-real time. This is something I have attempted to accomplish for years with various financial software tools like FactSet, Bloomberg and Eikon but have never been able to do to my satisfaction. But after taking an online course in Python programming (and with a lot of help from ChatGPT) I finally have the tools to realize my vision. While I suspect this project will be completed during the fourth quarter, most of the benefits are likely to begin accruing in the first quarter of next year. I will keep you updated on my progress.
Performance
During the third quarter of 2023, Kehlet Capital Management’s concentrated micro-cap composite declined 11.19%, underperforming the benchmark which fell 5.17%.
Our largest contribution to performance came from Chase Corp. (CCF), which increased 4.96%. As a reminder, Chase is a manufacturer of protective materials such as tapes, sealants, adhesives, and coatings used for high reliability applications across a broad range of markets. During the third quarter, Chase announced an agreement to be acquired by KKR, an investment management company, for $1.3 billion, or $127.50 per share. Though the deal has yet to be closed, shareholders approved the transaction on Friday, October 6th and it is expected to be completed during the fourth quarter.
We have owned shares in Chase since the inception of Kehlet Capital Management in 2017. At the time of this writing, it has slightly outperformed the benchmark, including dividends, during our more than six years of ownership – returning an average of nearly 6% annually compared to just under 5% for the index. Though this is a satisfactory result, I believe it would have been even better in the long run had the company not been acquired. The good news is the timing of the deal appears fortuitous, since it is coinciding with a down market and an increasing number of potential buying opportunities. Therefore, I am optimistic I will be able to redeploy the capital into more attractive opportunities once the deal is closed. I am currently monitoring several of these opportunities and will keep you posted on my progress.
Our largest detractor to performance was Astronics Corp. (ATRO), which declined 20.14%. Last quarter, I noted how the airline industry had nearly recovered to pre-COVID levels and that Astronics’ momentum would likely continue into the second half of 2023. And in the third quarter the company reported revenue growth of 32.6%, its first operating profit in nearly three years, and strong bookings growth of nearly 40% year-over-year. As such, management reiterated its previous guidance for full year revenue growth of 20% - 27%, with “expectations of achieving the higher-end of the range.” CEO Peter Gundermann added that “demand remains strong” and he expects “our year end to be busy with shipments… setting up for another strong year of improvement in 2024.”
So why did the stock decline? Honestly, I’m not entirely sure. My best guess is that the increase in bond yields during the quarter drove the overall decline in the stock market, which dragged highly indebted companies – such as Astronics – down more than less indebted companies. However, I believe the aerospace and travel industries are in a much stronger economic position than those with customers who are more sensitive to interest rates (e.g., housing, automotive, and durable goods). As such, I believe Astronics’ momentum will continue for the foreseeable future and the stock remains an attractive risk-reward trade-off at this level.
Portfolio Activity
No adjustments to portfolio weights were made during the quarter.
Conclusion
Though the third quarter of 2023 was disappointing from both an absolute and relative performance perspective, I believe short-term fluctuations in stock prices are of little concern, except for the opportunities they provide to capitalize on mispricing’s. Sometimes these mispricing’s are to the high side and sometimes they are to the low side. But what matters most is the fundamentals (e.g., growth, profitability, and ROIC) of the businesses we own. And they remain strong. Though Mr. Market seems to disagree – and his stubbornness can be frustrating – I believe his continued mispricing of our portfolio will ultimately prove to be one of the best things that could have happened to us. Because long-term returns will be better for it. But only time will tell. Thank you again for supporting Kehlet Capital Management, and please do not hesitate to contact me should you have any questions or comments.
| Number of holdings | 10 |
|---|---|
| Median market cap | $402M |
| Weighted avg. market cap | $369M |
| Fonar Corp. (FONR) | 27.0% |
|---|---|
| Climb Global Solutions (CLMB) | 21.1% |
| Astronics Corp. (ATRO) | 12.6% |
Disclosures to Performance Results
Actual composite performance results represent the performance of fully discretionary accounts managed by Kehlet Capital Management (KCM) during the corresponding time period. The composite performance results reflect time-weighted rates of return, the reinvestment of dividends and other account earnings. The reinvestment of dividends and other earnings may have a material impact on overall returns.
Past performance is not indicative of future results and the performance of a specific individual client account may vary substantially from the composite performance results. Therefore, no current or prospective client should assume that future performance will be profitable, or equal either the KCM composite performance results reflected above, or the performance results for any of the comparative index benchmarks provided.
For reasons including variances in portfolio account holdings, variances in the investment management fee incurred, market fluctuations, the date on which a client engages KCM’s investment management services, and any account contributions or withdrawals, the performance of a specific client’s account could vary substantially from the indicated KCM composite performance results. A portion of each account can be actively managed in an attempt to respond to changing conditions.
All performance results have been compiled solely by KCM, are unaudited, and have not been independently verified. Therefore, the performance data could be wrong. Information pertaining to KCM’s advisory operations, services, and fees is set forth in KCM’s current Form ADV Part 2A disclosure brochure, a copy of which is available from KCM upon request.
iShares IWM is an exchange-traded fund (ETF) measuring the performance of approximately 2,000 small-cap companies. It serves as a benchmark for small-cap stocks in the United States.
KCM managed accounts may own assets and follow investment strategies which cause them to differ materially from the composition and performance of the ETF shown as a benchmark. The ETF was chosen for its accessibility, transparency, independence, and relevance to KCM’s investment strategy, but there may be other indices that are more appropriate or applicable to the Concentrated Micro-cap Strategy. The historical index performance results are provided exclusively for comparison purposes only, so as to provide general comparative information to assist an individual client or prospective client in determining whether a specific Portfolio meets, or continues to meet, his/her investment objective(s). It should not be assumed that account holdings will correspond directly to any of the comparative indexes.
Different types of investments and/or investment strategies involve varying levels of risk, and there can be no assurance that any specific investment or investment strategy (including the investments purchased and/or investment strategies devised by KCM) will be either suitable or profitable for a client’s or prospective client’s portfolio and may result in a loss of principal. Accordingly, no client or prospective client should assume that the above portfolios (or any component thereof) serve as the receipt of, or a substitute for, personalized advice from KCM, or from any other investment professional.